
Archer-Daniels-Midland has had an impressive run over the past six months as its shares have beaten the S&P 500 by 8.8%. The stock now trades at $85.11, marking a 25.2% gain. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Archer-Daniels-Midland, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Archer-Daniels-Midland Not Exciting?
Despite the momentum, we’re sitting this one out for now. Here are three reasons why ADM doesn’t excite us, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
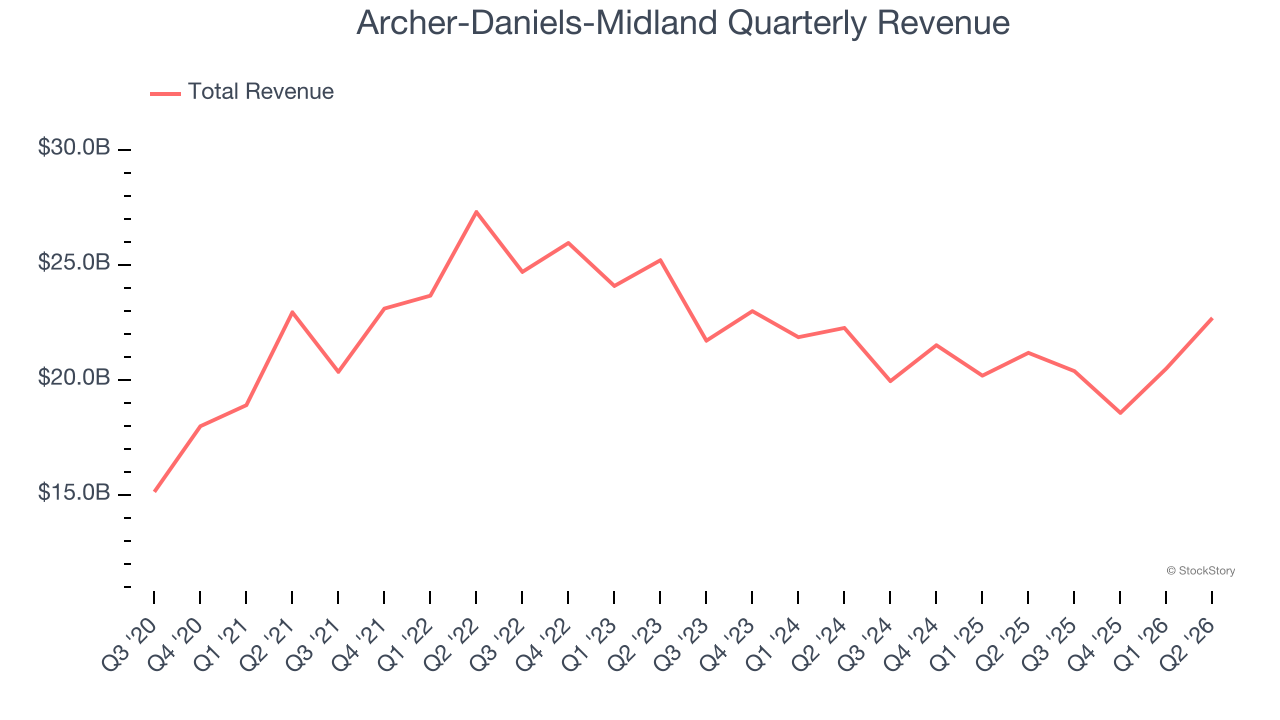
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last three years, Archer-Daniels-Midland’s demand was weak and its revenue declined by 6.3% per year. This was below our standards and is a sign of lacking business quality.
2. Low Gross Margin Reveals Weak Structural Profitability
At StockStory, we prefer high gross margin businesses because they indicate pricing power or differentiated products, giving the company a chance to generate higher operating profits.
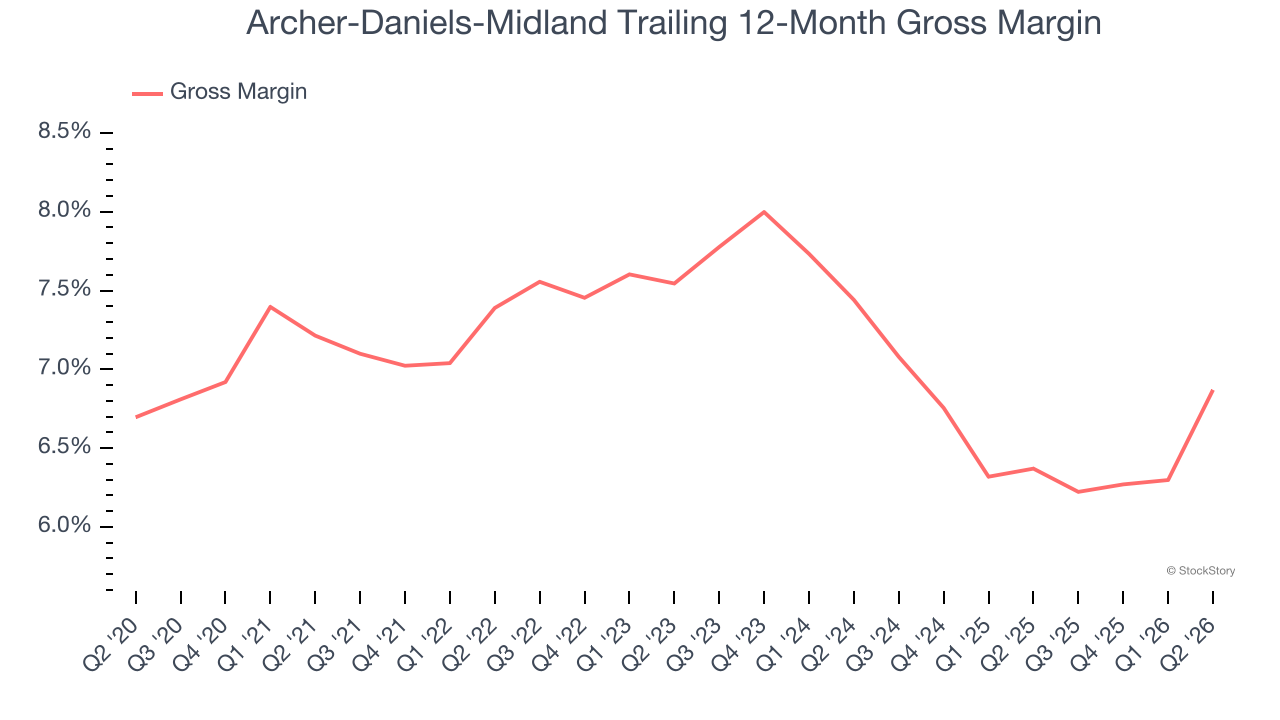
Archer-Daniels-Midland has bad unit economics for a consumer staples company, signaling it operates in a competitive market and lacks pricing power because its products can be substituted. As you can see below, it averaged a 6.6% gross margin over the last two years. That means Archer-Daniels-Midland paid its suppliers a lot of money ($93.38 for every $100 in revenue) to run its business.
3. EPS Trending Down
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
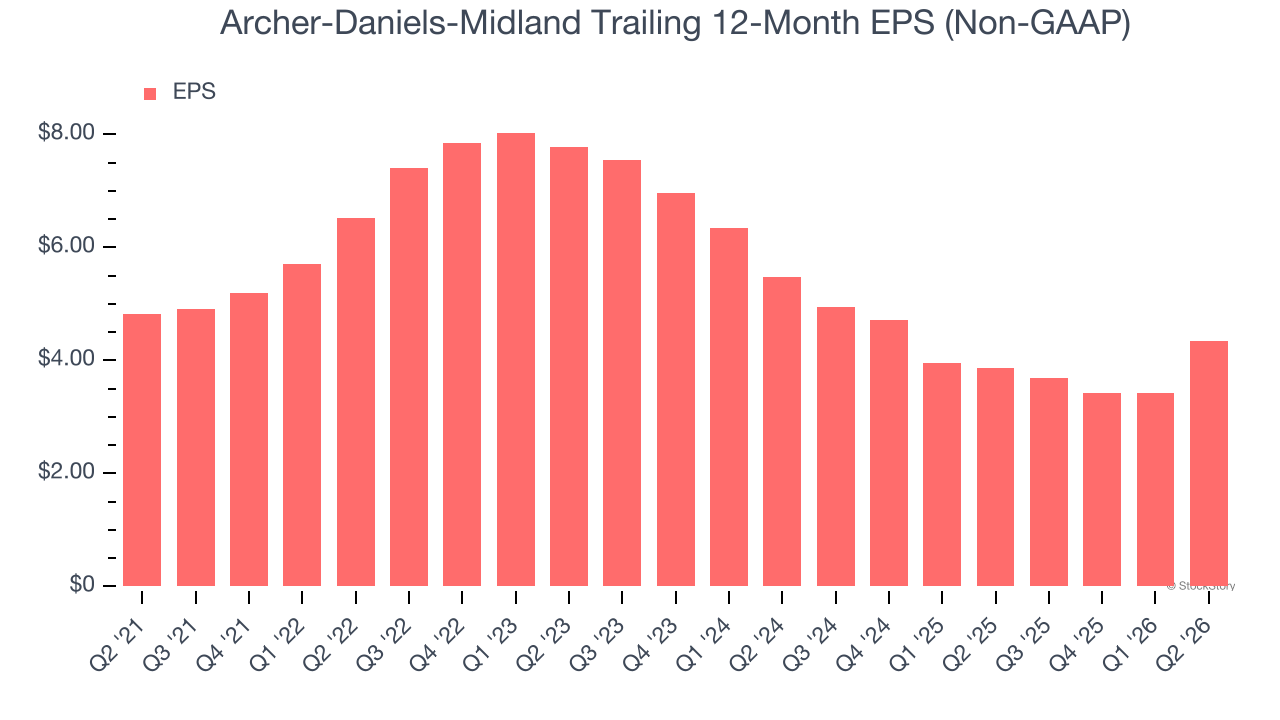
Sadly for Archer-Daniels-Midland, its EPS declined by 17.6% annually over the last three years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
Final Judgment
Archer-Daniels-Midland isn’t a terrible business, but it isn’t one of our picks. With its shares outperforming the market lately, the stock trades at 14.7× forward P/E (or $85.11 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Like More Than Archer-Daniels-Midland
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.